Recent CBSA customs notices and D-Memorandum revisions should not all be handled as equivalent regulatory changes. Some create a new duty or eligibility exposure; others clarify an existing requirement, change a reporting process or update the terminology used in CARM. For importers in Toronto, Mississauga and Brampton, the practical question is not simply whether a memorandum was revised. It is what kind of change occurred and which control should respond.
First separate the changes by legal and operational effect
A useful first review divides the recent material into four groups:
- New financial measures: rules that can change the amount payable on an import, such as the U.S.-origin surtaxes and the safeguard surtax on specified wood products.
- Preferential or classification treatment: changes that can alter whether a tariff treatment is available or how goods are classified.
- Reporting and eligibility requirements: updates affecting rail movements, bonded warehouses, courier transport or regulated products.
- Reference and process revisions: changes to D-Memorandum language, forms, CARM terminology or policy presentation that may require procedure updates without creating a new duty by themselves.
This distinction matters because the response to a new surtax is not the same as the response to a memorandum consolidation or a clarification of existing policy.
Changes that can alter the amount payable
U.S.-origin surtaxes
Effective September 8, 2026, specified U.S.-origin goods became subject to a surtax rate of 15%, 25% or 50%, depending on the applicable tariff classification. The measure applies to commercial and casual imports, including listed goods shipped to Canada through a third country. The importer accounts for the surtax code and amount on the Commercial Accounting Declaration through CARM, EDI or API. Goods already in transit to Canada on September 8 may be excluded when the importer can substantiate the in-transit status with shipping or cargo-control records. CBSA Customs Notice 26-23
The control response should begin with a product-level review of origin and tariff classification. Importers should also identify shipments that were in transit on the effective date and preserve the documents supporting that position. A commercial invoice alone may not answer the transit question; the relevant shipping and cargo-control record should be retained and matched to the transaction.
Wood cabinets, vanities and subassemblies
From July 31, 2026, certain wood cabinets, vanities and specified subassemblies became subject to a 25% provisional safeguard surtax. The affected goods are identified through listed tariff items. The amount is entered in field 87, “Safeguard,” of the Commercial Accounting Declaration rather than the ordinary surtax field, using safeguard code 26169A. The measure was initially set for up to 200 days from July 31, subject to the Canadian International Trade Tribunal inquiry. CBSA Customs Notice 26-17
Kitchen, bathroom and home-improvement suppliers should therefore test both the classification decision and the accounting field. A product master that identifies the tariff item but does not distinguish the safeguard field can still produce an incorrect declaration.
Changes that affect eligibility or classification
United Kingdom preferential treatment
Effective September 1, 2026, the United Kingdom, Channel Islands and Isle of Man were added to the Customs Tariff for the Comprehensive and Progressive United Kingdom Tariff treatment. Eligible goods may receive the applicable preferential tariff treatment. Importers should review origin qualification, tariff classification and supporting documentation before claiming the treatment. The updated T2026-2 Customs Tariff became available in all formats on September 16, 2026. CBSA Customs Notice 26-22
This is not the same control problem as a surtax. The central question is whether the goods qualify for the preference and whether the claim is supported. Importers should not apply the treatment solely because the commercial supplier is located in the United Kingdom; the origin analysis and supporting records remain relevant.
Electric motorcycle and cycle descriptions
Effective August 6, 2026, the description of tariff item 8507.60.20 changed from “electrically-powered motorcycles” to “motorcycles or cycles with an electric motor.” Importers of potentially affected electric motorcycles, cycles and related battery products should review existing classification decisions. The CBSA notice specifically indicates that importers with advance tariff-classification rulings should consider whether the description change affects those rulings. CBSA Customs Notice 26-21
The appropriate response is a targeted SKU and ruling review, not an automatic reclassification of every battery-powered product. The file should show the product description, technical specifications, current tariff treatment and the conclusion reached after comparing the revised wording.
Changes that clarify reporting or release conditions
Rail in-transit movements
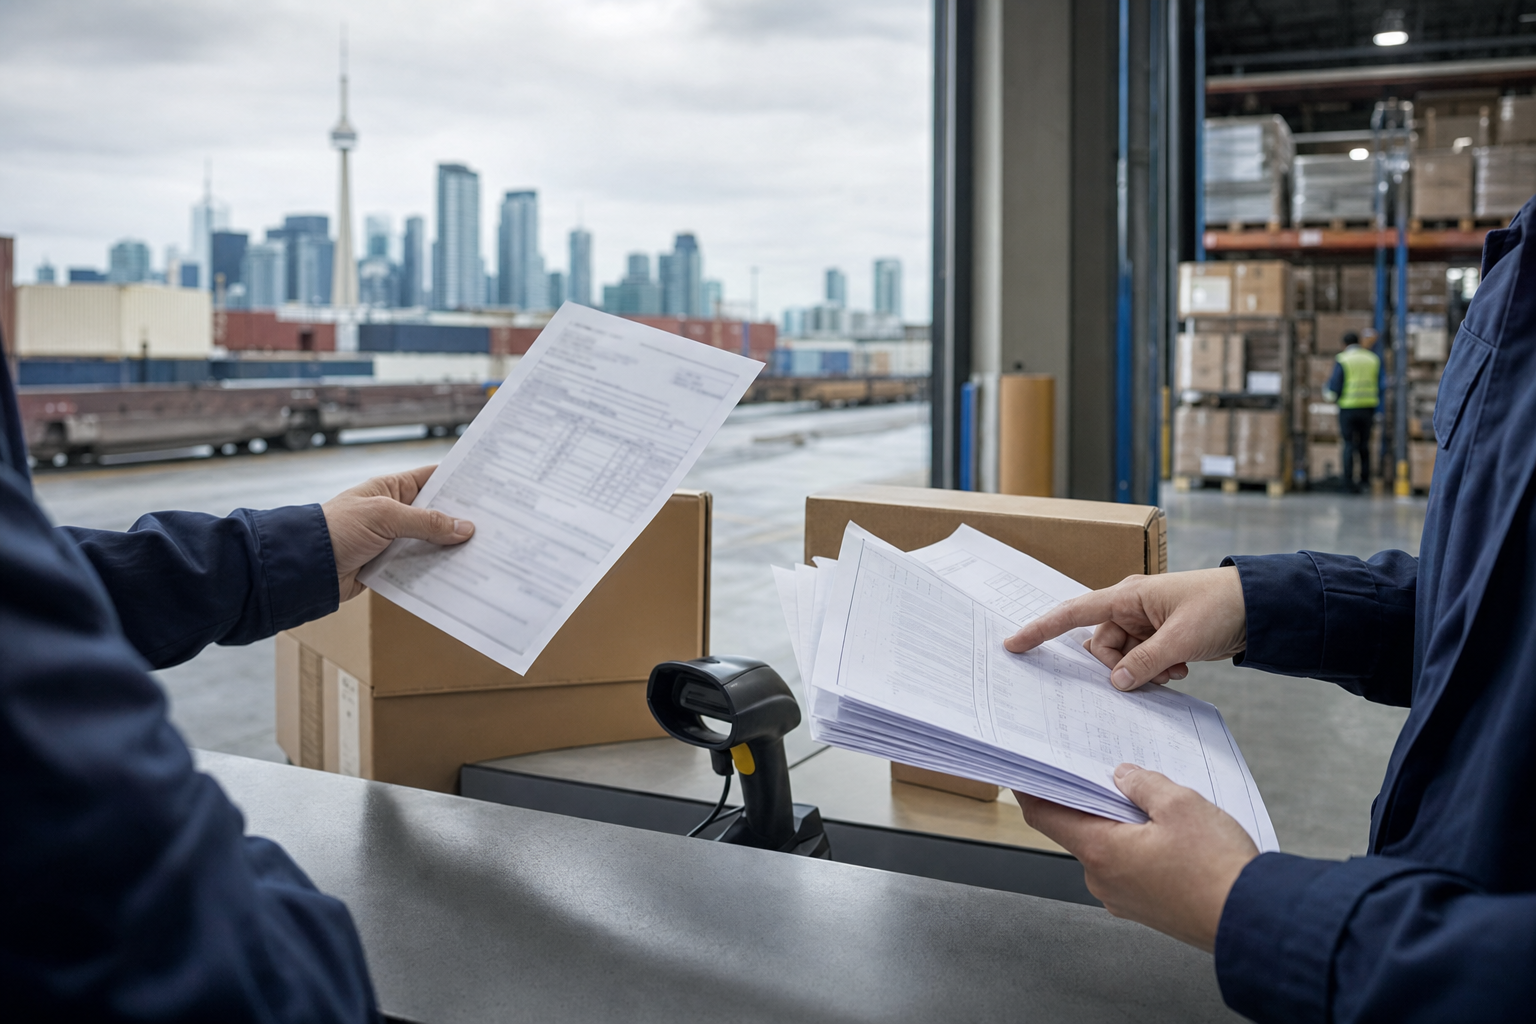
Customs Notice 26-16, issued July 10, 2026, clarified reporting procedures for rail cargo moving through Canada between foreign points, from the United States through Canada and back to the United States, and from Canada through the United States and back to Canada. For certain movements, carriers must use the “Rail In-transit Manifest” movement type in ACI/eManifest, provide complete cargo information within the prescribed rail timeframe or use the BSF708 paper process where permitted. CBSA stated that the guidance would later be incorporated into Memorandum D3-6-6. CBSA Customs Notice 26-16
Importers using rail should discuss routing and data ownership with the carrier or forwarder. The key review is whether the movement is being treated as an in-transit movement and whether the manifest information corresponds to the actual route. This is especially relevant where freight serving the GTA is routed through both Canadian and U.S. gateways before reaching a Toronto-area distribution point.
TRQ goods in bonded warehouses
On August 21, 2026, CBSA clarified that goods subject to tariff-rate quotas entered into a customs bonded warehouse require a valid, shipment-specific Global Affairs Canada import permit covering the date the goods leave the warehouse to qualify for the “within access” rate. CBSA described this as a clarification of existing policy, not a policy change. If the permit is unavailable at warehouse entry, the importer accounts for the applicable treatment on the Type 10 Commercial Accounting Declaration and later submits an adjustment before using a “within access” Type 20 or 21 ex-warehouse declaration. CBSA Customs Notice 26-20
For a bonded warehouse operator or importer in Mississauga, Brampton or elsewhere in the GTA, the practical control is permit-to-shipment matching. The warehouse entry date and the eventual removal date should not be treated as interchangeable when the permit must cover the date of removal.
D-Memorandum revisions that mainly change the working reference
Several revisions update the framework used by importers, brokers and other trade-chain participants without creating a single new rate applicable to every shipment:
- D4-1-4: revised July 6, 2026, to include the Customs Sufferance Warehouse Enrolment Form BSF897. Applications are submitted through the CARM Client Portal, and CBSA aims to decide complete applications within 60 business days. D4-1-4
- D19-6-3: revised July 24, 2026, to update regulated-product information following Amendment 18 to the Energy Efficiency Regulations, with related housekeeping changes. D19-6-3
- D10-15-15: revised August 14, 2026, by merging the previous D10-15-15 and D10-15-21 memoranda into one memorandum covering tariff items 9958.00.00 and 9959.00.00. D10-15-15
- D11-6-8: revised September 9, 2026, to reflect CARM Release 3 and the replacement of the former B3-3 and B2 forms with the Commercial Accounting Declaration. It applies to verification work involving origin, tariff classification or value for duty. D11-6-8
- D19-12-1: revised September 2, 2026, to update the definition of “temporary residents” in vehicle-importation guidance. D19-12-1
These revisions still warrant review, but the response should be proportionate. A changed form, merged memorandum or updated definition may require procedure, training or template changes; it does not automatically mean that every open transaction has a new duty liability.
What to discuss with your customs broker
- Which imported products, if any, fall within the U.S.-origin surtax or wood-product safeguard measures?
- Do any U.K.-origin purchases qualify for the CPUKT treatment, and what origin records support the claim?
- Do current tariff classifications, advance rulings and product descriptions remain appropriate after the electric-cycle wording change?
- For rail freight, who owns the in-transit movement type, manifest data and supporting route records?
- For TRQ goods, can the permit be matched to the shipment and the date of warehouse removal?
- Which internal forms, product databases, verification files and broker instructions still refer to superseded B3-3 or B2 processes?
The objective is to classify each revision before assigning work. New duty measures need a financial and declaration review; preferential treatment needs an origin and classification review; reporting notices need carrier and data-process controls; and D-Memorandum housekeeping needs document and procedure maintenance.