Canada formally published two U.S.-related surtax measures on September 23, 2026, but both state that they came into force on September 8. For importers in Toronto, Mississauga and Brampton, the practical issue is therefore not simply when the Canada Gazette notice appeared. It is whether shipments and accounting records need to be assessed against the September 8 operative date.
What changed, and when
The United States Surtax Order (2026) imposes surtaxes of 15%, 25% or 50% on specified U.S.-origin goods according to tariff-item schedules. The order covers goods in sectors including appliances, dairy, furniture, apparel, electronics, machinery, steel and aluminum. Its stated coming-into-force date is September 8, while registration and publication occurred on September 23. The Canada Gazette order also contains related remission amendments and exclusions, including qualifying goods that were already in transit to Canada when the order came into force.
A separate amendment revises the earlier United States Surtax Order (Steel and Aluminum 2025). Its schedules distinguish covered U.S.-origin steel and aluminum products subject to 25% or 50% surtax. The amendment also states that goods in transit on the coming-into-force date retain the previously applicable surtax treatment. It was likewise registered and published on September 23 but took effect on September 8. The steel and aluminum amendment lists primary metals, flat-rolled products, bars, tubes, pipes, fabricated steel goods and aluminum products at the tariff-item level.
Why the date distinction matters
Importers generally need to separate three dates in their shipment files: the date the goods entered the relevant Canadian process, the date the goods were in transit if an exception is being considered, and the legal effective date in the order. The September 23 publication date is not the same as the September 8 coming-into-force date.
This distinction is especially important where a shipment falls within a tariff-item schedule but may qualify for an in-transit rule. A commercial description such as “machinery,” “aluminum parts” or “steel components” is not enough to determine treatment. The orders use tariff-item schedules and origin rules, so an importer reviewing exposure should match the goods to the applicable tariff classification and confirm U.S. origin before deciding how the surtax is handled.
- Review entries and shipments connected to the September 8 effective date.
- Identify whether the goods are covered by the general U.S. surtax order or the steel and aluminum amendment.
- Check whether a stated in-transit provision applies to the shipment.
- Keep the tariff classification, origin analysis and shipment-status evidence together.
What GTA importers should review now
Industrial and manufacturing supply chains
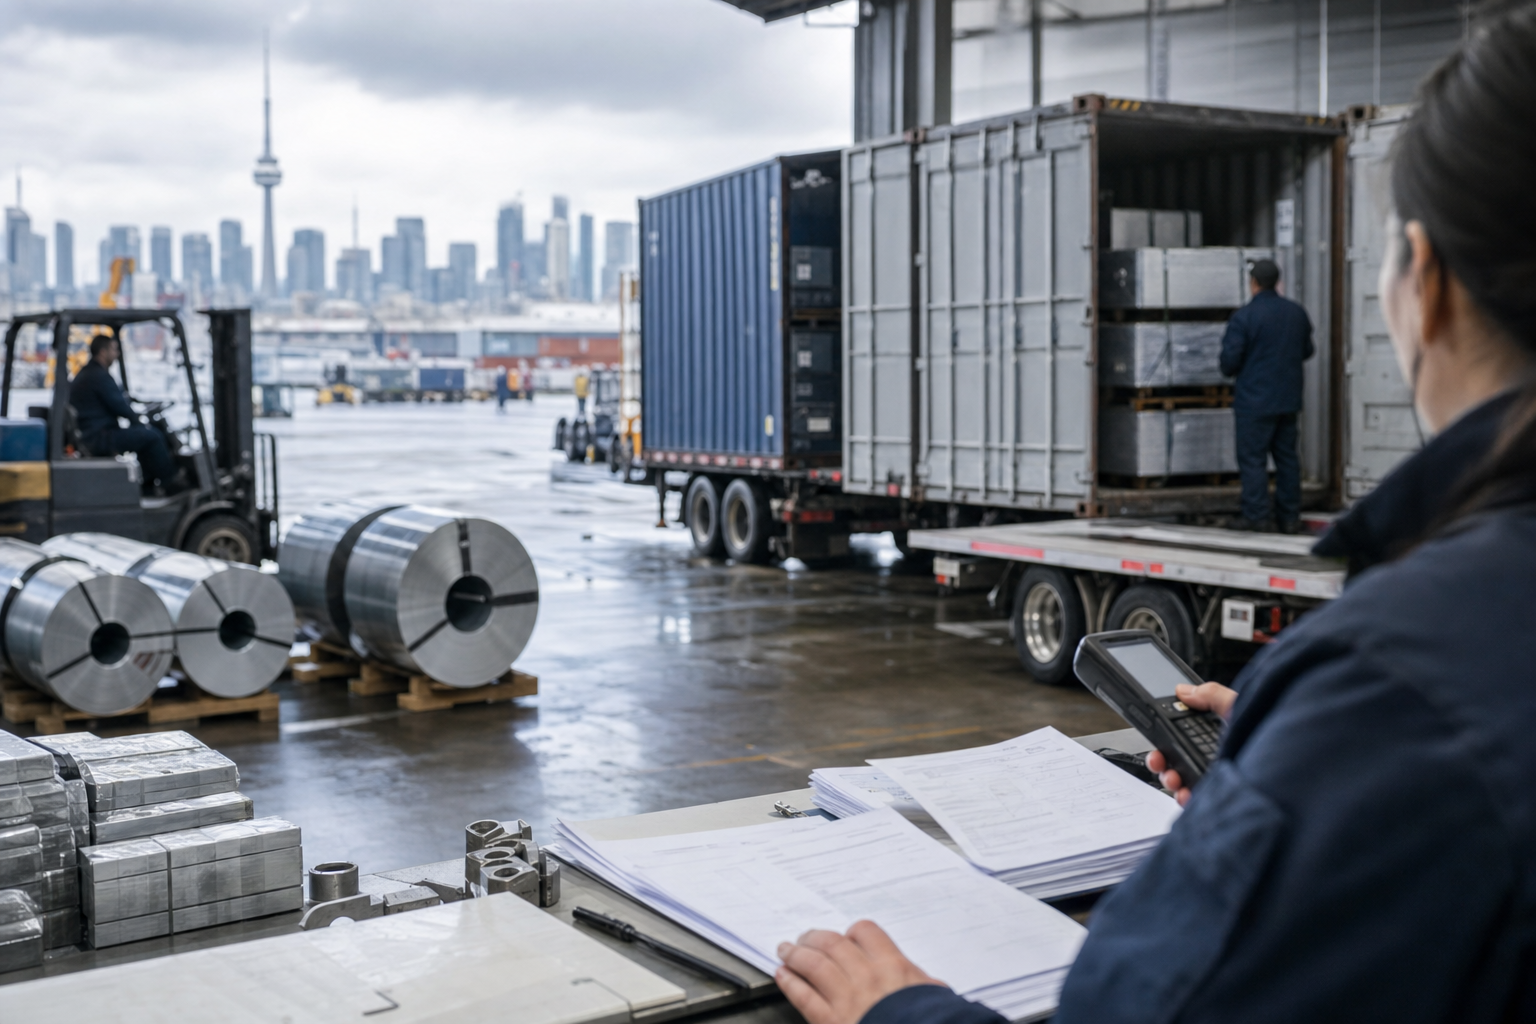
The steel and aluminum amendment is particularly relevant to manufacturers, distributors, construction-supply businesses, automotive suppliers and industrial importers in Southern Ontario. A shipment moving into a Mississauga or Brampton facility may have been planned using the publication date, while the applicable order points to September 8. Importers should therefore compare affected purchase orders, entry data and inbound shipment records against the revised schedules.
The same review applies to covered goods moving through highway, air or rail gateways serving the Toronto area. The measure applies federally at Canadian ports, so the gateway used does not by itself determine whether the surtax applies.
Documentation and accounting review
Importers who claim that goods were in transit on September 8 are generally expected to retain records supporting that position. The relevant evidence will depend on the shipment and the order, but the review should be tied to the exact tariff item, origin and transit status rather than only to an invoice description.
The September 9 revision to CBSA Memorandum D11-6-8 is a separate compliance development, not a new duty rate. It updates verification procedures for origin, tariff classification and value for duty to reflect CARM Release 3 and the replacement of B3 and B2 forms with the Commercial Accounting Declaration. The revised memorandum is relevant when organizing the records used to support the surtax analysis.
Other September changes to keep separate
Not every recent change has the same effect as the U.S. surtax orders. CBSA’s revised T2026-2 Customs Tariff added the United Kingdom, Channel Islands and Isle of Man to Comprehensive and Progressive United Kingdom Tariff treatment effective September 1, 2026; the updated files became available September 16. Importers claiming CPUKT treatment generally need to confirm origin eligibility, tariff classification and proof of origin. CBSA’s customs notice and the 2026 tariff files provide the relevant source material.
CBSA also temporarily permitted authorized Courier Low Value Shipment Program participants to use third-party air carriers that are not Partners in Protection certified, effective September 14, 2026. Those carriers must remain bonded and present CLVS shipments at the designated sufferance warehouse, while the courier must continue to maintain active PIP certification for air mode. The change concerns authorized couriers and their third-party carriers rather than ordinary commercial importers directly, but it may affect courier arrangements through Toronto Pearson. The CLVS notice sets out that temporary change.
For the U.S. surtax measures, the immediate control point is the September 8 effective date. Importers should treat the September 23 publication as the point at which the formal text and schedules became available, not automatically as the first date requiring review.